

Buy and hold can fail when a company’s business weakens, its competitive position erodes, or the reasons for owning it no longer apply. That’s when buy and hold does not work: patience can help investors endure volatility, but it cannot repair deteriorating fundamentals or guarantee that a stock will recover.
It’s reasonable to question the approach when prices swing sharply or a stock remains down. But volatility alone doesn’t make a long-term strategy outdated, and reacting to every decline can undermine the discipline it requires.
This article explains how buy and hold aims to capture long-term growth, why volatility tests investors’ resolve, and how poor-quality stocks can put the strategy at risk. You’ll learn to distinguish temporary price pressure from signs that a company’s long-term prospects have changed.
Key Takeaways
- Set written actions for market declines in advance so decisions follow a plan rather than a moment of stress.
- Separate broad market volatility from changes in a company’s financial health, competitive position, and growth prospects.
- Review individual stock holdings over time; a long holding period cannot fix a business whose fundamentals have deteriorated.
- Use historical market recoveries as context, not a timetable: recovery periods vary, and past patterns don’t determine what happens next.
- Consider whether your time horizon, need for portfolio income, and tolerance for volatility fit a buy-and-hold approach.
#128 Why “Buy and Hold” Doesn’t Always Work?
Buy and hold seeks long-term appreciation by keeping investments through rising and falling markets. It can falter when the holding no longer fits the investor’s goals or a company’s prospects deteriorate.
Performance Across Bull and Bear Markets
Buy and hold means keeping investments through rising and falling markets rather than repeatedly trying to time each move. A downturn can test whether an investor’s time horizon and risk capacity match the portfolio. Someone investing for a distant goal may have more time to withstand volatility than someone who needs to withdraw funds soon.
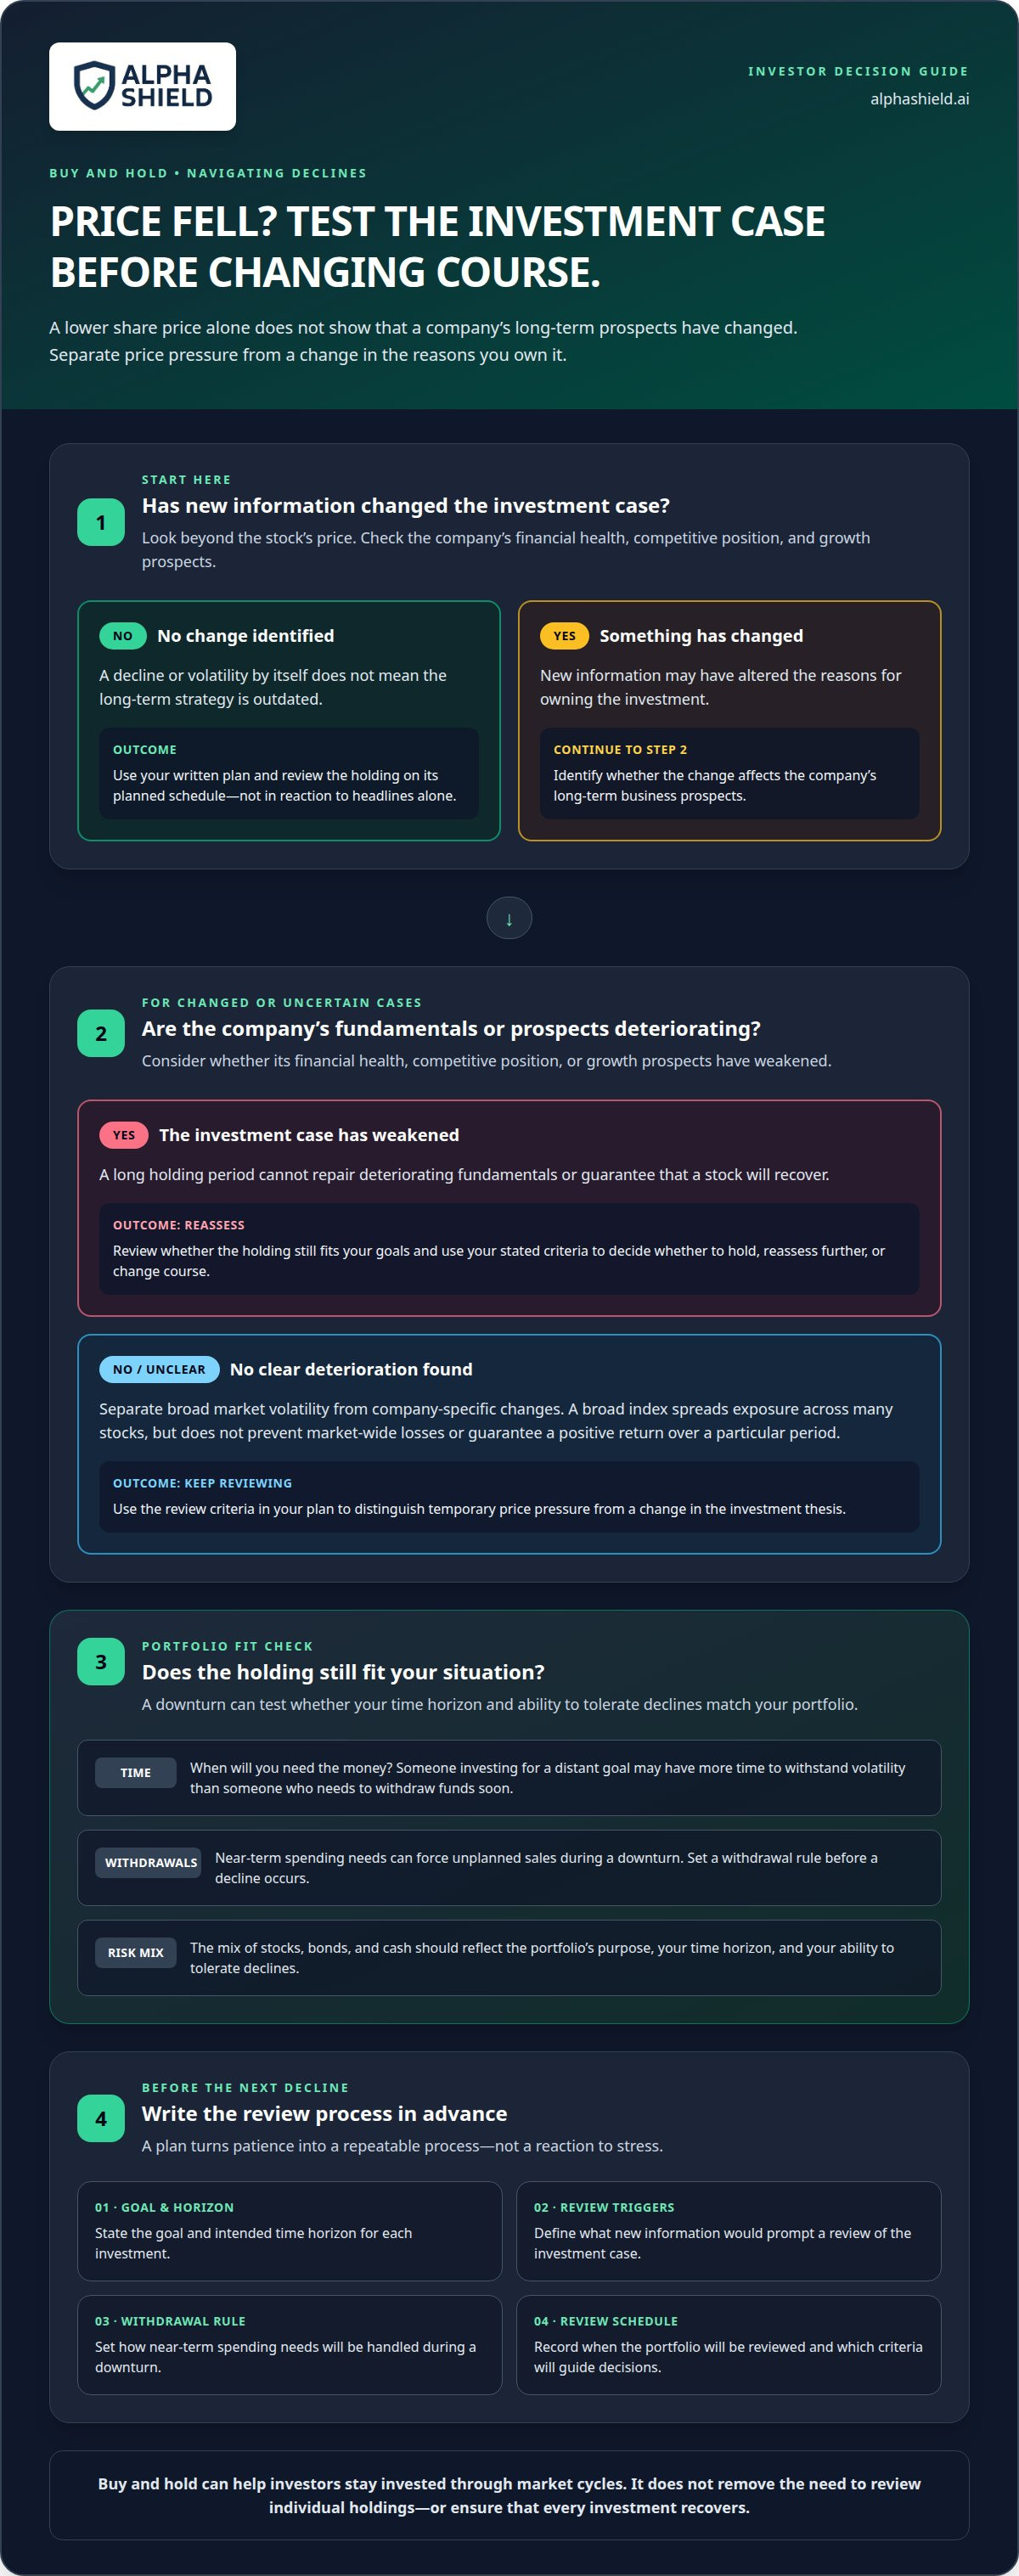
Market declines can challenge the strategy even when an investor intends to stay invested. Selling after a drop can turn a temporary decline in market value into a realized loss; buying back later means deciding when prices are attractive again. To assess when buy and hold does not work, ask whether the investment’s underlying case has changed, not simply whether its price has fallen.
Broad Indexes and Market-Wide Investing
A broad index spreads exposure across many stocks, so one company’s decline has less influence than it would in a portfolio holding only that stock. This diversification helps explain why buy and hold can suit market-wide investing: investors own a range of businesses rather than depending on one company’s future. It does not prevent market-wide losses or guarantee a positive return over a particular period.
Asset allocation still matters. A portfolio’s mix of stocks, bonds, and cash should reflect its purpose, time horizon, and the investor’s ability to tolerate declines. Inflation also reduces the purchasing power of future gains, so an account balance can rise while buying less. For example, someone investing for retirement should consider both portfolio growth and the future cost of planned spending.
Planning for Declines and Volatility
A written plan for market declines sets out actions before stress makes decisions harder. It turns patience into a process: investors can distinguish ordinary price movements from a change in the investment thesis instead of reacting to headlines alone.
- State the goal and time horizon for each investment, such as retirement savings intended for a distant date.
- Define what would prompt a review, such as new information that changes a company’s financial health or competitive position.
- Set a rule for withdrawals, so near-term spending needs don’t force unplanned sales during a downturn.
- Record when the portfolio will be reviewed and which criteria will guide any decision.
These steps don’t eliminate volatility. They give investors a consistent basis for deciding whether to hold, reassess, or change course.
Market Efficiency and Long-Term Investing
The efficient-market hypothesis holds that available information is reflected in security prices, making it difficult to consistently identify mispriced investments through timing alone. For buy-and-hold investors, this supports following a long-term plan instead of reacting to every price change. Active investing takes a different route: investors select securities or adjust positions in an attempt to outperform, but more transactions can add costs and decision points.
Neither approach guarantees superior returns. Buy and hold relies on staying invested through market cycles; active investing depends on the quality and execution of decisions. Warren Buffett’s shareholder letters offer one widely discussed perspective on long-term ownership, but individual stocks still need ongoing scrutiny. The right choice depends on an investor’s objectives, discipline, and ability to assess holdings.
Buy-and-hold definition and long-term price appreciation
Buy and hold means purchasing investments and keeping them through market fluctuations rather than trading frequently to capture short-term price moves. The strategy relies on time in the market, long-term business growth, and reinvested dividends or interest to support compounding. An investor might regularly add to a diversified mutual fund throughout a career, allowing contributions and returns to build over time. The aim is long-term growth, not profit from predicting every market turn.
Individual stocks make the distinction clear. An investor who buys a company based on its financial health and growth prospects holds only while the investment case remains sound. A historical Apple example describes buying 100 shares at $18 in January 2008 and holding until January 2019, when the stock was $157. The example reports a return of nearly 900% over just over 10 years. It illustrates one outcome, not a forecast or a reason to ignore changing company fundamentals.
Retirement planning also depends on when capital will be needed. A market decline could force an investor to sell shares to meet near-term expenses, leaving fewer assets invested for a later recovery. Consider near-term spending needs separately from long-term investments when deciding how much market risk a portfolio can carry.
Taxes can influence the result in a taxable account. In the United States, investors in taxable accounts who hold investments for more than 1 year generally qualify for long-term capital gains tax rates, which are generally lower than short-term rates taxed as ordinary income, according to the Internal Revenue Service. Selling sooner can change how a gain is treated. Tax consequences depend on the account and transaction, so consider them alongside the investment decision.
Frequent short-term trading creates more decisions. Each trade requires a view on timing, price, and what comes next. Acting on past performance can lead investors to buy funds after strong returns and sell after weak ones. That pattern can reduce returns if an investor exits before a recovery or repeatedly switches positions. Education helps clarify the difference between a planned review and a reaction to market noise.
Buy and hold is a method, not a rule to keep every asset indefinitely. Set a review point for each investment: does its original rationale still hold, does it serve the retirement goal, and will the money be needed soon? If the answers change, reassessing the holding is more disciplined than treating patience as a substitute for judgment.
Emotional discipline during volatility
Volatility tests whether investors can stick with a long-term position as prices move sharply. Buy and hold means accepting that market cycles include advances and declines, not treating every drop as a signal to sell. Decisions made under stress can replace an investment process with a short-term reaction. The challenge is not to ignore price changes, but to assess them against the reason for owning the asset.
Benjamin Graham wrote about patience and discipline in the 1940s. His emphasis remains relevant to investors who feel pressure to act whenever headlines turn negative. A sudden decline can make selling seem like the safest choice, while a fast rally can tempt investors to chase the latest winner. Both responses can pull a portfolio away from its intended purpose. Discipline means using consistent criteria, not predicting each move correctly.
Separate the emotional trigger from the investment decision. When a position falls, pause and ask what has changed: the market price, the company’s prospects, or your own needs? If only the price has moved, that alone doesn’t tell you whether the original rationale still holds. If the company’s financial health or competitive position has weakened, reassessment may be necessary. This distinction helps prevent “hold forever” from becoming a substitute for judgment.
During a volatile situation, use a short review sequence:
- Identify the event causing concern, such as a broad market decline or company-specific news.
- Compare the new information with the reasons for buying the position.
- Consider whether the investment still fits the portfolio’s time horizon and purpose.
- Make a decision based on those criteria, rather than the urge to act immediately.
This process can reduce impulsive selling without requiring investors to dismiss risk. For example, a retirement investor with a long time horizon may view a broad decline differently from someone who needs to fund near-term spending. Their situations differ, as does their ability to remain invested. Patience is most useful when the holding still fits the goal and the investor can withstand its fluctuations.
Emotional discipline also means resisting speculative bubbles. Rising prices can tempt investors to abandon a considered approach and buy assets simply because others seem to be profiting. A written rationale gives each position a reference point: what the investor expects, which risks matter, and what evidence would change the view. That record can help distinguish confidence grounded in analysis from enthusiasm driven by recent performance.
Buy and hold is not a command to tolerate every decline indefinitely. It asks investors to avoid reflexive market timing while staying alert to meaningful changes. If volatility alone prompts a sale, the investor may exit during a temporary setback. If evidence changes the investment case, holding without review can be equally undisciplined. The objective is measured action, not inaction.
Risks of holding poor-quality individual stocks
Buy and hold can apply to individual stocks, but this carries company-specific risk that a diversified index fund spreads across many businesses. A stock can lose value because its business weakens, even while the wider stock market performs differently. Passive ownership doesn’t remove the need to research a company or reassess whether it still belongs in a portfolio.
This distinction matters because broad market exposure can dilute problems affecting one company. A business might lose customers, struggle to compete, or weaken financially. If those changes undermine the original reason for buying its shares, holding them automatically is not a sound investment process. For example, an investor who bought a retailer for its growth prospects should reconsider if the company’s outlook has materially changed.
“Buy and hold” describes a holding period, not a test of quality. Before keeping a stock, revisit the original rationale and compare it with current company information. Is the business still financially healthy? Does it retain a competitive advantage? Are its growth prospects consistent with the investor’s expectations? These questions focus attention on the company rather than its latest share-price move. They also help distinguish a temporary market setback from a deteriorating investment case.
A practical review can consider several areas without treating any single signal as conclusive:
- Business health: Look for changes in the company’s financial condition and ability to sustain its operations.
- Competitive position: Assess whether customers still have clear reasons to choose the company over alternatives.
- Growth outlook: Compare current prospects with the assumptions behind the original purchase.
- Portfolio role: Consider whether one stock has become too important to the investor’s capital, future income, or goals.
For example, an investor holding a company for its dividends may need to reconsider if the business weakens and the expected income becomes less dependable. Another investor may hold the same stock for growth, but face a changed thesis if its expansion prospects fade. The company’s role matters. Decide whether to keep or sell based on the investment’s purpose and the evidence, not on a desire to avoid admitting an earlier assessment was wrong.
A broad index contains many different stocks, while an individual holding depends on one company’s fortunes. Diversification can reduce the impact of a single business failing, but it doesn’t make every index or investment safe. A stock may remain weak for reasons that time alone won’t resolve. Research each holding, document what would change the thesis, and reassess when company facts conflict with the original case. Patience supports long-term investing; it cannot repair poor business quality.
How long have U.S. stocks taken to recover after major market crashes?
There is no single recovery timetable for U.S. stocks. The answer changes with the crash, the starting point, and whether recovery means regaining a previous price peak. The S&P 500 lost roughly 37% of its value in 2008. In March 2020, markets fell more than 30% in a matter of weeks. Those episodes show why a long-term investor needs to plan for declines without assuming each one resolves on the same schedule.
Time horizon affects how a crash feels in practice. Historical S&P 500 returns over one-year, five-year, and even ten-year periods have varied more than rolling 20-year periods. Shorter periods have included meaningful losses. Rolling 20-year periods going back to the mid-20th century historically produced positive results, though outcomes varied. These observations describe the index’s history, not a deadline for an individual investor’s recovery.
Recovery also depends on what you measure. An index may return to an earlier price level, while an investor’s account value differs because of contributions, withdrawals, or the timing of purchases. Someone who keeps investing during a decline has a different experience from someone who sells or withdraws funds. Income needs matter too: taking money from a portfolio during a downturn can reduce how long it lasts.
For a retiree, a recovery that takes years can matter more than it does for someone accumulating investments. Planned spending may require selling shares before prices rebound. Recovery history should therefore inform a portfolio’s time horizon and cash planning, not be treated as a promise that a particular holding will regain its peak by a chosen date. The asset mix and need for withdrawals shape the practical impact.
Use historical crashes as planning scenarios, not forecasts. A written review can clarify what would happen if stocks fell, whether near-term spending would remain covered, and which conditions would prompt a portfolio reassessment. It can also distinguish a broad decline from company-specific damage. An index’s recovery history cannot establish that a struggling individual stock will recover alongside the market.
Buy and hold still carries timing risk when it’s time to sell. An investor who must sell during a downturn may lock in losses, even if the market later rises. Conversely, leaving a position solely because prices fell can mean missing a rebound. A plan should connect each investment to its purpose, the investor’s time horizon, and the conditions that warrant a change.
Historical S&P 500 data offers context, not certainty. The 2008 decline, the rapid fall in March 2020, and the varied results across one-, five-, and ten-year periods show why recovery expectations should remain tied to actual needs. Investors should distinguish index-level history from an individual stock’s prospects, then make decisions using a defined process rather than a calendar guess.
Alpha Shield
Alpha Shield helps investors assess market volatility and drawdown risk through a systematic market perspective. The Alpha Shield Market Signal, Market crash and drawdown tool, and Alpha Shield Dashboard provide indicators focused on market risk management, not a judgment on whether a particular company’s stock is worth holding. They can be relevant when broad market conditions make it harder to distinguish a temporary decline from a change in overall risk. Use that perspective alongside your own goals, time horizon, and review of individual companies. Market signals don’t remove uncertainty or replace a decision process; they add another input for investors considering how market conditions affect a long-term approach.
Contact Alpha Shield to discuss how its market signals fit your approach to managing volatility.
Make your next portfolio review deliberate
Use your next review to turn a broad investing philosophy into a decision you can explain. Choose one holding and write down its role in your portfolio, the assumptions that support owning it, and the evidence that would change your view. This makes it easier to distinguish a revised investment case from a reaction to market noise.
Ask a focused question: when does buy and hold not work for this investment? The answer depends on whether the business still serves its purpose in your portfolio and whether your goals have changed. A review won’t remove uncertainty, but it can make your next decision more consistent and easier to revisit.
If market risk is part of that decision, Alpha Shield’s daily market signal and dashboard can provide a systematic market perspective. Use them as inputs to your process, alongside your assessment of each company and your financial objectives.
Clear criteria create a steadier path forward, one considered decision at a time.
Frequently Asked Questions
Is buy and hold investing outdated?
No. Buy and hold remains a long-term approach, but it isn’t right for every investment or investor. Its usefulness depends on the asset’s quality, the investor’s goals, and the ability to remain invested through downturns. Someone holding a diversified fund for a distant goal faces a different decision from someone relying on one company’s future. Assess the strategy against its purpose, not its age.
Does buy-and-hold mean I should never sell?
No. Holding an investment indefinitely regardless of new information can turn discipline into neglect. Selling may make sense when an investment no longer serves its intended purpose, a company’s outlook has changed, or an investor needs to adjust the portfolio. A written sell strategy can define what evidence triggers a review. That keeps decisions tied to investment criteria instead of a short-lived price move or strong emotional reaction.
Is buy-and-hold appropriate for retirees?
It can be, but retirees need to consider how withdrawals interact with market declines. Someone who needs portfolio income soon has less flexibility than someone who can leave investments untouched. Plan near-term spending separately from assets intended for longer-term growth, and consider a more conservative allocation and cash reserves. The right balance depends on income sources, spending needs, investment horizon, and tolerance for fluctuations.
What about market timing? Isn’t it better to sell high and buy low?
In theory, selling high and buying low sounds straightforward. In practice, it requires correctly identifying both points, and waiting in cash can mean missing some of the market’s best-performing days, significantly reducing long-term returns. A timing decision also creates another decision: when to reinvest. A written plan can help distinguish deliberate portfolio changes from attempts to predict every short-term market move.
When does buy and hold investing underperform or fail?
Buy and hold can underperform when an investment’s costs or fundamentals work against long-term results. A mutual fund with high management expenses can face a persistent drag, while a company losing its competitive position may not recover simply because an investor keeps holding. Chasing funds with strong past returns can also hurt results if investors buy after gains and sell after declines. Review both investment quality and ongoing costs.
What are the risks of buy and hold during long bear markets?
A long bear market can leave investors facing extended losses, delayed goals, and pressure to sell. The risk is greater if withdrawals continue while portfolio values are down, because fewer assets remain invested for a possible recovery. Inflation can also reduce what an unchanged account balance can buy. Consider how your spending needs, income sources, and ability to stay invested would respond to a prolonged decline before choosing an allocation.
When should investors sell a buy-and-hold investment?
Consider selling when the original reason for owning an investment no longer applies, its role in the portfolio has changed, or your financial needs have shifted. A planned review can weigh company fundamentals, diversification, and the purpose of the money. Reviewing at least once a year keeps a holding visible without encouraging constant trading. A price decline alone doesn’t show whether the investment case has changed.
How do fees and taxes affect long-term buy-and-hold returns?
Fees reduce the portion of investment returns that remains in an account, so recurring fund expenses deserve attention over long holding periods. Taxes can arise when investments are sold in taxable accounts, while fewer transactions can reduce how often gains are realized. Passive funds such as S&P 500 index portfolios often have turnover rates below 5%. Compare costs and consider the tax effect before changing holdings.


