
A portfolio can look diversified on paper and still leave you uneasy about downside risk. That concern is one reason investors explore alternatives to modern portfolio theory. MPT offers a disciplined way to balance expected return against volatility, but it relies on historical relationships and treats price fluctuation as its central measure of risk. Those assumptions can feel incomplete when markets shift sharply. Diversification matters, but it can’t remove every source of loss.
There isn’t one universal replacement. Some approaches change how risk is measured; others change how assets are selected or account for investor behavior. This guide compares major frameworks by purpose, evidence, costs, and implementation demands. The practical question isn’t which approach promises certainty, but which assumptions you understand and can maintain without relying on forecasts or frequent trading. You’ll also see how systematic market-risk signals can support a disciplined review as conditions change, as an input alongside portfolio construction rather than a substitute for a long-term investment plan.
Key Takeaways
- Use diversification to manage how assets interact, while recognizing it cannot eliminate portfolio losses.
- Compare alternatives to modern portfolio theory by the risk each measures and the decisions it changes.
- Distinguish downside-risk measures, volatility, drawdowns, and factor exposure before selecting an approach.
- Evaluate a strategy against your objectives, time horizon, liquidity needs, and tolerance for losses.
- Use systematic market signals as one input to portfolio reviews, not as a substitute for a long-term investment framework.
What Modern Portfolio Theory does, and what its assumptions leave open
Modern Portfolio Theory (MPT) is a framework for balancing a portfolio’s expected return against its measured risk. Its central insight is that an investment should be assessed not only on its own, but also on how it behaves alongside the rest of the portfolio. An asset with lower expected returns may still contribute value if its returns move differently from other holdings.
“Volatility measures variation in market prices; it doesn’t, by itself, tell you whether a loss will be permanent.” MPT commonly measures risk through variance or standard deviation, which captures how widely returns fluctuate. These measures help compare portfolios, but they don’t fully describe every risk an investor may face.
How MPT uses diversification and the efficient frontier
Combining assets with different return patterns can reduce overall portfolio volatility, depending on their weights and correlations. Correlation measures how closely two assets’ returns move together. If their movements differ, losses in one holding may be partly offset by another. The effect isn’t guaranteed, and diversification cannot remove market-wide risk or prevent losses.
The efficient frontier is a set of modeled portfolios that offer the highest expected return for a given level of estimated risk, or the lowest estimated risk for a chosen expected return. It’s a comparison tool, not a forecast. Its position depends on inputs such as expected returns, volatility, and correlations, often estimated from historical data. Change those estimates and the modeled trade-offs can change too.
Where investors question MPT’s assumptions
MPT is most useful when its assumptions are treated as modeling choices, not certainties. The framework requires investors to define their objectives and estimate risk and relationships among assets. But correlations can shift. Holdings that appeared to diversify one another in calmer periods may fall together during market stress, making historical relationships an imperfect guide.
Measured volatility is also different from liquidity risk, concentration risk, or the experience of a deep drawdown. An asset may show limited price movement while being difficult to sell at a fair price. A portfolio may have moderate overall volatility but still depend heavily on one sector or source of return. These risks call for separate consideration alongside standard deviation.
That doesn’t make diversification or MPT useless. MPT gives investors a structured way to assess portfolio-level trade-offs. Its limits show why the alternatives to modern portfolio theory deserve comparison by what they measure and which decisions they inform. Investor objectives can also extend beyond a single risk-return calculation: Behavioral Portfolio Theory considers how psychological factors shape investment decisions. The practical task is to understand what a model captures, what it leaves out, and whether its assumptions fit the investment plan.
Five alternatives to Modern Portfolio Theory, and the problem each addresses
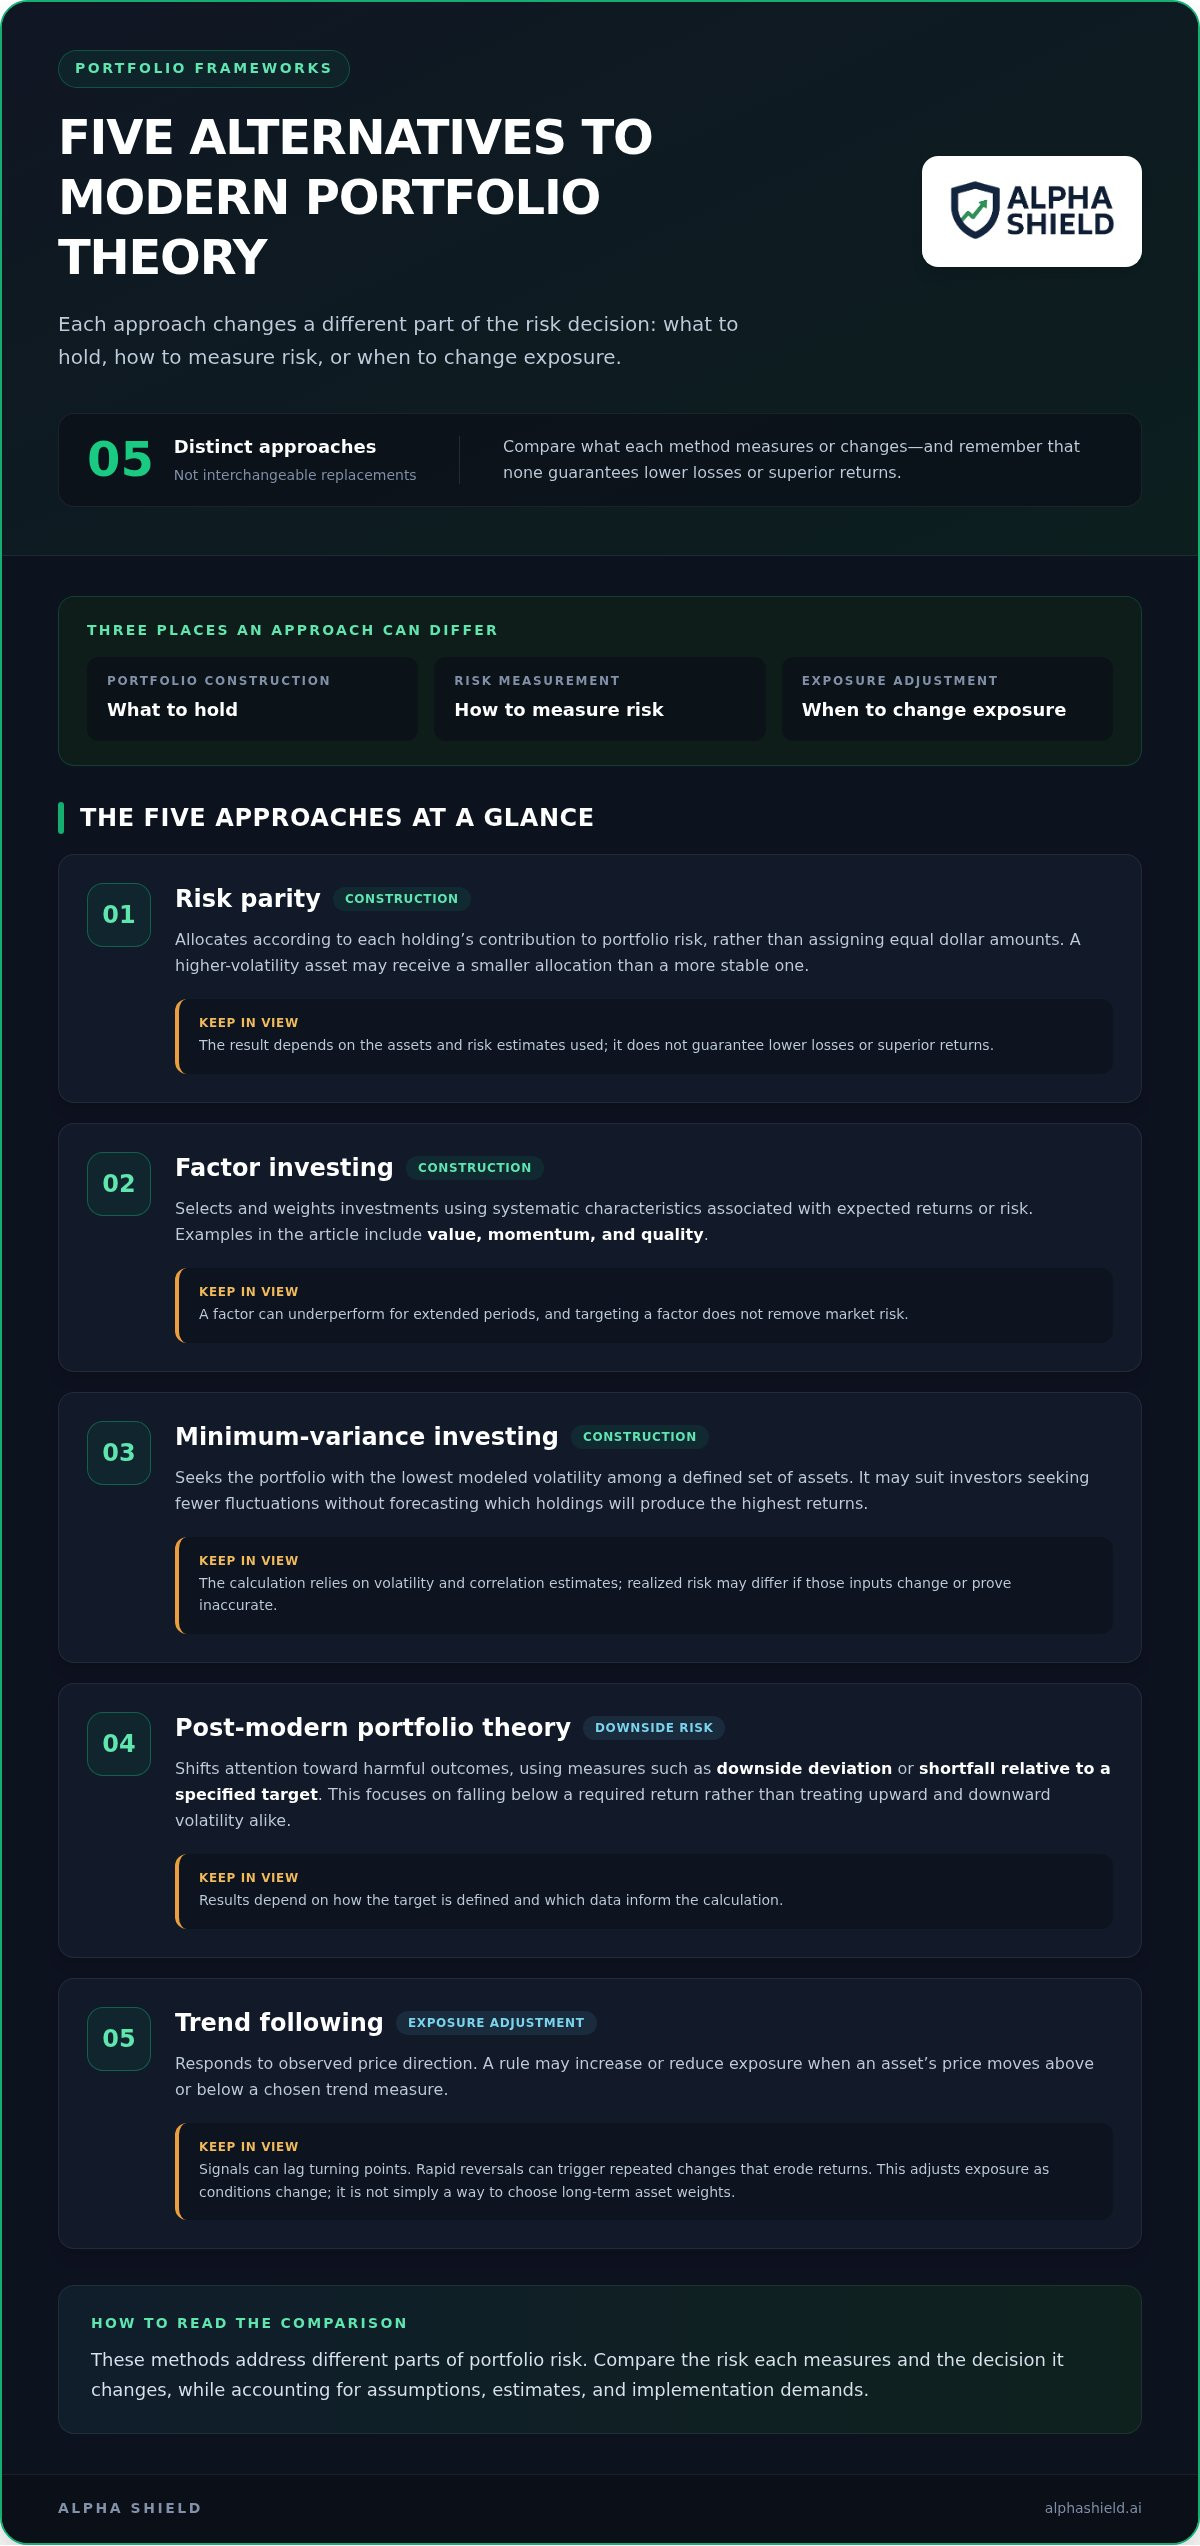
The alternatives to modern portfolio theory don’t solve the same problem. Some change how a portfolio is constructed; others focus on downside outcomes or adjust exposure in response to price trends. Each approach changes a different part of the risk decision: what to hold, how to measure risk, or when to change exposure. That distinction helps investors compare methods without treating them as interchangeable replacements.
Portfolio-construction alternatives: risk parity, factors, and minimum variance
Risk parity allocates according to each holding’s contribution to portfolio risk, rather than assigning equal dollar amounts. A higher-volatility asset may receive a smaller allocation than a more stable one. The aim is to balance risk contributions across holdings, but the result depends on the assets and risk estimates used. It doesn’t guarantee lower losses or superior returns.
Factor investing selects and weights investments based on systematic characteristics associated with expected returns or risk, such as value, momentum, or quality. It can make a portfolio’s sources of return more explicit. But a factor can underperform for extended periods, and targeting a factor doesn’t remove market risk.
Minimum-variance investing seeks the portfolio with the lowest modeled volatility among a defined set of assets. It may suit investors looking to reduce fluctuations without forecasting which holdings will produce the highest returns. The calculation still relies on estimates of volatility and correlation. If those inputs change or prove inaccurate, realized risk may differ from the model.
Post-modern portfolio theory and trend-following approaches
Post-modern portfolio theory (PMPT) shifts attention toward harmful outcomes, using measures such as downside deviation or shortfall relative to a specified target. This can better reflect an investor’s concern about falling below a required return than treating upward and downward volatility alike. Results still depend on how the target is defined and which data inform the calculation.
Trend following responds to observed price direction. A rule might increase or reduce exposure when an asset’s price moves above or below a chosen trend measure. This is a way to adjust exposure as conditions change, not simply a method for choosing long-term asset weights. Signals can lag a turning point, and rapid reversals can trigger repeated changes that erode returns.
The practical divide is clear. Risk parity, factor investing, and minimum-variance methods primarily shape portfolio construction. Trend following is a rule-based exposure adjustment, while downside-risk measures change how outcomes are evaluated. An investor may use a construction framework and a monitoring rule together, but each adds assumptions, costs, and decisions to maintain. The Alpha Shield Market Signal provides a systematic market-risk input for reviewing market conditions. It doesn’t dictate portfolio weights or guarantee protection from losses.
How the main alternatives compare on risk, evidence, and practical demands
Compare each approach by the risk it measures, the decision it changes, and the work required to maintain it. Portfolio-construction methods set weights or exposures. A risk-management overlay, such as a trend rule, can adjust exposure as market behavior changes. Neither category is automatically superior. The useful choice depends on your objectives, time horizon, liquidity needs, and ability to follow the method through difficult periods.
| Approach | Purpose | Core inputs | Main risk addressed | Implementation burden |
|---|---|---|---|---|
| Post-modern portfolio theory | Evaluate outcomes below a target | Returns and a defined shortfall threshold | Downside deviation or shortfall | Set a relevant target and measure results consistently |
| Risk parity | Balance contributions to portfolio risk | Volatility, correlations, and asset weights | Uneven risk contribution | Estimate risk and rebalance allocations |
| Factor investing | Target systematic return or risk characteristics | Factor definitions, security data, and portfolio rules | Concentration in particular factor exposures | Monitor exposures, turnover, and periods of underperformance |
| Minimum variance | Seek the lowest modeled volatility | Volatility, correlations, and asset constraints | Portfolio-level price fluctuation | Maintain estimates and check resulting concentrations |
| Trend following | Adjust exposure in response to price direction | Price history and signal rules | Exposure to persistent adverse trends | Apply rules consistently and manage turnover and reversals |
Which approach focuses on which kind of portfolio risk?
Risk parity and diversification focus on how holdings contribute to combined portfolio risk. Factor investing highlights exposure to systematic characteristics, which can become a source of concentration. Downside measures focus on losses below a chosen threshold. Volatility measures variation in returns; drawdown measures a decline from a prior peak to a later low. These are related, but not interchangeable. No single metric captures every form of investment risk, including liquidity constraints or the difficulty of staying invested through a decline.
Trend-following rules respond to observed market behavior. They don’t require certainty about why prices are moving or what comes next. But signals can lag, and reversals can produce losses. They are better understood as exposure-adjustment rules than as forecasts.
What evidence and trade-offs should investors examine?
Backtests are conditional results, not guarantees. They depend on the data selected, assumptions, test period, and implementation choices, including fees, turnover, taxes, and investable constraints. Check whether a strategy remains plausible after these frictions and whether its rules could have been followed in practice. Also consider sensitivity to different market environments, data-mining risk, and the possibility of extended underperformance.
Historical evidence describes results under specific past data and assumptions; it cannot guarantee future performance, especially when market conditions, costs, or implementation differ. The alternatives to modern portfolio theory are most useful when judged against a defined objective and a realistic operating plan, not ranked in the abstract.
How to evaluate an alternative for your own investment plan
Choose a method by the decision it helps you make, not by how compelling its recent results look. The alternatives to modern portfolio theory differ in what they measure and how they may change a portfolio. Use this sequence to test fit before adopting one.
- Define your objective, horizon, liquidity needs, and loss tolerance. Separate the need for long-term growth from a need to access funds soon or limit the depth of a decline. A strategy that targets lower volatility may not address short-term cash needs.
- Identify what the method measures. Is it focused on price variation, losses below a target, drawdowns, factor exposure, or risk contributions? Name the risk clearly. A method cannot be judged against a concern it doesn’t measure.
- Specify the action it changes. Does it alter asset weights, select exposures, or adjust market exposure when conditions change? If the signal changes, determine in advance what portfolio decision follows and what does not.
- Set the operating rules. Define rebalancing triggers and frequency, monitoring responsibilities, and how the approach handles conflicting signals. Account for fees, turnover, taxes, and the practical limits of implementing trades.
- Write down the conditions for review. Specify what would indicate that the strategy’s assumptions or your own circumstances have changed. This helps distinguish a planned review from a reaction to alarming headlines.
Match the method to the investor’s actual objective
A return-seeking investor, someone managing volatility, and someone concerned about a deep drawdown may need different tools. Liquidity is a separate constraint: a strategy designed to reduce measured portfolio fluctuations doesn’t automatically ensure that assets can be sold when cash is needed.
Record the purpose in a written investment policy. For example, if the priority is maintaining access to funds, a method aimed mainly at factor exposure may not resolve the central concern. The policy gives you a reference point when market headlines create pressure to change course.
Stress-test assumptions before adopting a strategy
Examine performance across distinct market environments, not just one favorable period. Check which assets, dates, and assumptions shaped the test. A backtest can be sensitive to the selected period, rebalancing frequency, and whether costs are included. Consider how delayed, missed, or reversed signals would affect the rules in actual use.
Historical testing can inform an evidence-based market timing process, but it cannot establish that a pattern will persist. Treat evidence as conditional and document its limits. A systematic risk mitigation framework should clarify what prompts a review, rather than claim certainty about future markets.
Use systematic market-risk monitoring as an input to disciplined review, alongside a portfolio plan. Signals don’t guarantee protection from losses.
Where systematic market signals fit alongside portfolio theory
A portfolio framework and a market-risk signal serve different roles. Strategic asset allocation sets the portfolio’s intended mix of investments in line with an investor’s objectives and constraints. A systematic indicator monitors market conditions and may prompt a review of that plan. It isn’t a complete portfolio-construction system, and it doesn’t determine which individual securities to buy or sell.
Portfolio framework versus market-risk signal
Decide in advance what a signal is allowed to change. For example, an investor might use a change in market-risk conditions as a prompt to review portfolio exposure, confirm rebalancing rules, or reassess whether the investment policy still fits. The signal can inform that process without dictating a trade. Predefined rules help keep a review methodical rather than driven by the urgency of a headline.
Limits matter. A signal can be wrong, arrive after conditions have changed, or fail to flag a sudden shock. It cannot predict every market decline, remove market exposure, or prevent losses. Treat it as one monitoring input alongside a durable investment framework. That distinction also helps place market crash defense strategies in context: risk management can inform decisions, but it can’t make outcomes certain.
Alpha Shield’s role in disciplined risk monitoring
Alpha Shield Market Signal and the Alpha Shield Dashboard are designed to monitor market health and identify higher-risk periods. They provide a systematic risk-monitoring input that can support a disciplined review as conditions change. They don’t replace portfolio construction or specify individual security choices.
This long-term risk-management focus is distinct from day trading and shorting. A market signal should be interpreted within the investor’s own plan: if the indicator changes, the appropriate response depends on objectives, risk tolerance, liquidity needs, and rules set beforehand. If it doesn’t change, that alone doesn’t prove a portfolio is free from risk.
Signals don’t guarantee protection from losses. They may be mistimed or miss a rapid change in conditions, so investors should avoid treating any indicator as a promise of safety or a standalone decision system. Used with clear review rules, systematic monitoring can add structure without replacing the broader investment framework.
Make your next portfolio decision with discipline
The right framework is one you can explain, implement, and stay with when conditions become difficult. Use your investment policy as the anchor. Then decide whether an additional risk-monitoring input can make reviews more systematic without turning every market move into a reason to trade. The alternatives to modern portfolio theory are best considered in that practical light, not as promises of certainty.
Alpha Shield’s market-risk system began development in 2017 and launched in 2019. Its founders bring over 50 years of combined investment banking and global markets experience. The Alpha Shield Dashboard supports monitoring market health and risk. These tools can inform a disciplined review, but they can’t guarantee protection from losses or replace portfolio construction.
Build clarity into your process before the next period of uncertainty. A defined framework and measured review can help keep decisions aligned with your long-term objectives.
Frequently Asked Questions
What is the best alternative to Modern Portfolio Theory?
There’s no universally best alternative; the right fit depends on what your portfolio needs to do. For example, an investor funding regular withdrawals may prioritize limiting shortfall risk, while someone seeking a rule-based response to sustained price declines may examine trend following. Compare each method’s assumptions and operating demands against your written plan. Treat historical results as evidence to assess, not a forecast or promise.
Is Modern Portfolio Theory still relevant in 2026?
Yes. MPT remains useful as a way to reason about diversification and trade-offs between expected return and measured risk. An investor can use it as a baseline, then review whether its inputs still reflect the portfolio’s exposures and objectives. For example, a material change in spending needs may call for a fresh allocation review, even if market conditions haven’t changed. A framework should inform judgment, not replace it.
Can risk parity replace Modern Portfolio Theory?
Risk parity can serve as an alternative allocation approach, but it isn’t a universal substitute for MPT. Its usefulness depends on how risk contributions are estimated and how the portfolio is implemented. If an approach uses leverage, for instance, borrowing introduces additional exposure and financing considerations. Before adopting it, assess whether you can maintain its allocation rules through weak performance and how it fits with the rest of your investment policy.
What is the difference between MPT and post-modern portfolio theory?
MPT commonly evaluates risk through overall return variability, while post-modern portfolio theory focuses more directly on adverse outcomes, such as falling below a chosen target. Consider an investor who needs portfolio withdrawals to meet planned expenses: shortfall relative to that goal may be more relevant than price swings in either direction. The target matters, though. Set it to reflect a genuine objective, not a number chosen to make a strategy look favorable.
Does diversification protect a portfolio from market crashes?
Diversification can limit reliance on a single holding, but it can’t ensure that a portfolio avoids losses in a broad decline. A practical review is to identify what each holding is meant to contribute, then consider how the portfolio might behave if several exposures weaken at once. Also distinguish investments intended for long-term growth from funds needed for near-term spending. That makes potential liquidity pressure visible before a market disruption occurs.
Can market timing outperform a buy-and-hold portfolio?
It can, but consistent outperformance isn’t assured. A fair comparison should use the same period and account for the full timing process, including when the strategy re-enters after reducing exposure. For example, a rule that exits during a decline may also remain cautious during a rebound. Include transaction costs and taxes where relevant, and compare outcomes with a suitable benchmark. Past results alone can’t establish what the next market cycle will deliver.
How should investors compare alternatives to Modern Portfolio Theory?
Start with one specific concern, such as funding a planned withdrawal or limiting exposure to a particular return driver. Then compare candidate methods against that concern using consistent measures and a benchmark suited to the portfolio. Review whether the evidence includes periods beyond those used to develop the rules, and note any assumptions you can’t verify. This makes the comparison more useful than choosing a strategy based on a single strong historical result.


